
The expenses listed on this type of account are those that your financial have a tendency to believe whenever choosing if or not you can afford to repay a home loan. Your lender have a tendency to examine these costs whenever figuring, also, the dimensions of out-of a mortgage, as well as how high away from a payment, you might conveniently afford.
Their mortgage repayments whether getting an initial home loan otherwise property equity financing or almost every other sorts of 2nd financial normally score given that greatest month-to-month bills for many people. If you’re obtaining an alternative financing, their lending company includes your own estimated month-to-month mortgage payment into the their formula of monthly bills.
Lenders think about almost every other continual mortgage commission as a key part of your monthly obligations. Fundamentally, one mortgage that requires you to definitely build a payment is actually believed element of your debt if you find yourself obtaining a great home loan.
Loan providers look at your personal credit card debt, too. They’ll utilize the full minimum called for money you have to generate monthly in your credit cards to determine their month-to-month credit debt. For example, for those who have about three handmade cards, one having an important minimal monthly payment of $100, another type of that have at least needed fee regarding $50 and you can a 3rd that needs that shell out at least out-of $forty five monthly, your own bank tend to consider carefully your monthly personal credit card debt to be $195, the sum of those people minimum monthly premiums.
The debt-to-money ratio is actually a switch number when you find yourself trying to get an interest rate
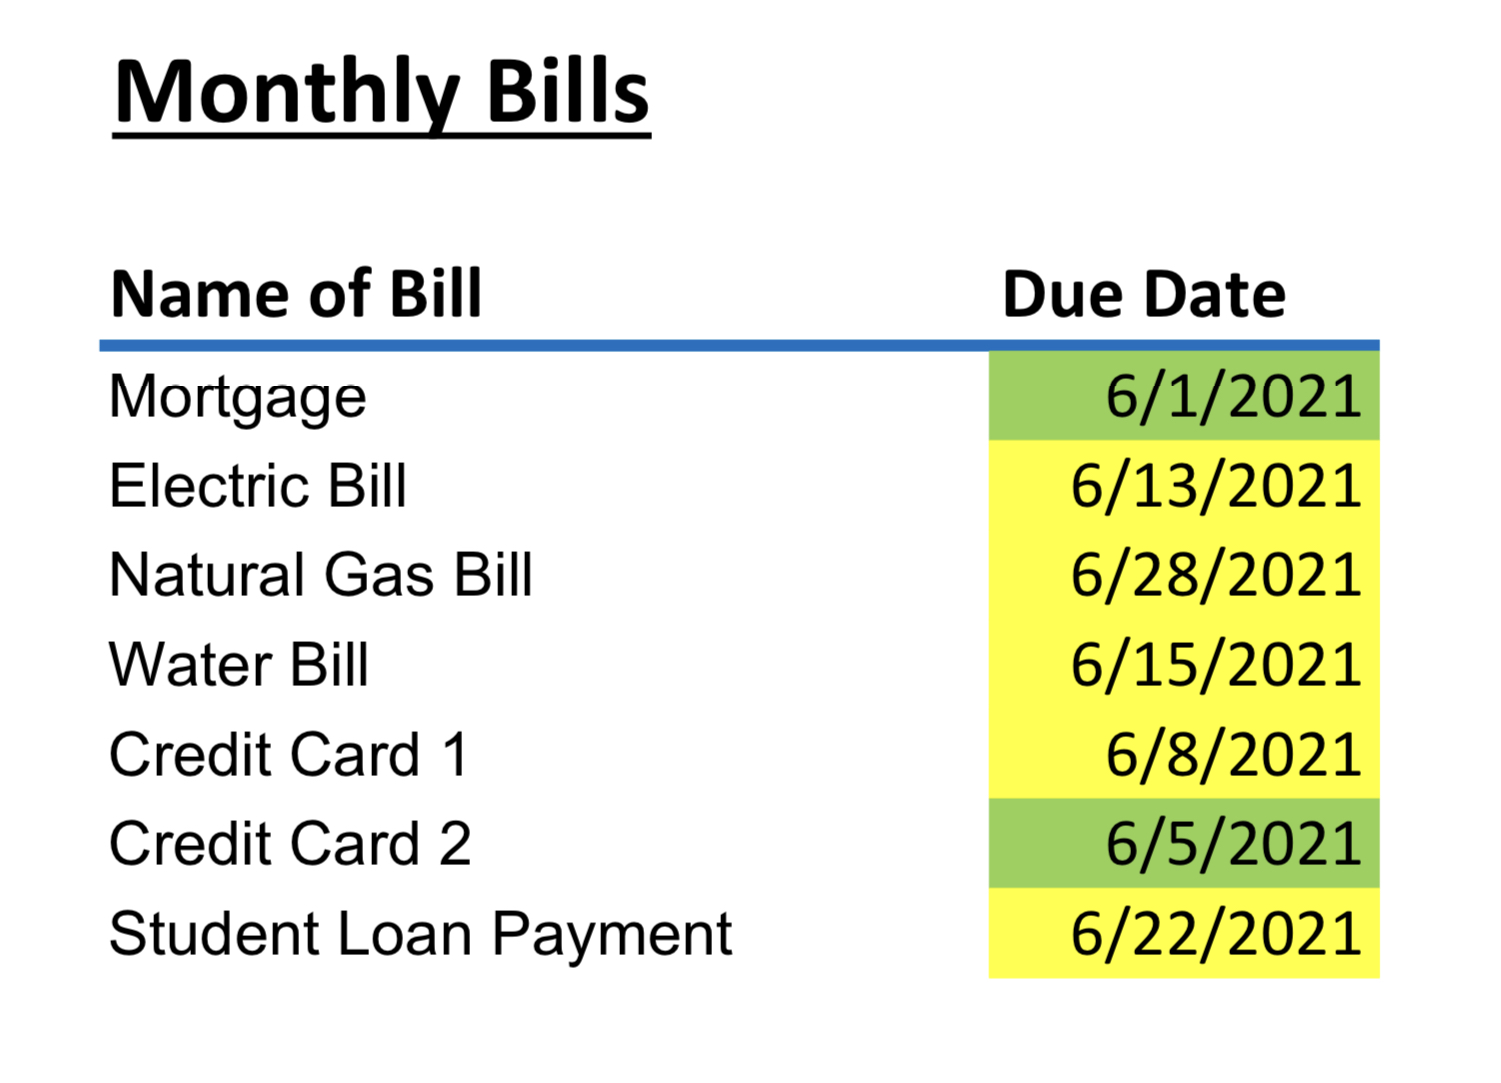
When you are divorced, you could generate monthly alimony or youngster assistance money. Lenders think about these money in your month-to-month financial obligation as you need to cause them to become each month, even after you add an interest rate commission to your expenses.
Lenders uses the month-to-month financial obligation totals when calculating your debt-to-earnings (DTI) ratio, a switch profile that identifies besides whether your be eligible for home financing but how large that loan are.
Which proportion measures how much of the disgusting monthly money was eaten right up by the monthly expense. Most mortgage lenders need their month-to-month expense to help you equal no longer than simply 43% of the disgusting month-to-month income.
In order to estimate the debt-to-money proportion, basic influence their terrible monthly income. This is your monthly income before taxes is taken out. It does is their salary, impairment money, Social Safeguards payments, alimony money or any other money that can come for the each month.
After that dictate the monthly expense, as well as your estimated brand new homeloan payment. Divide such debts into your gross monthly money so you’re able to estimate your own DTI.
Here’s an example: Say your own terrible month-to-month money are $eight,000. State you will also have $step one,000 within the monthly costs, made mainly out-of requisite credit card payments, a personal bank loan payment and you may an auto loan payment. You are obtaining home financing that feature an enthusiastic estimated payment per month from $2,000. Because of this loan providers commonly consider carefully your monthly expenses to help you equivalent $step three,000.
Divide one to $3,000 for the $7,000, and you also assembled a good DTI simply a little more 42%. You might decrease your DTI because of the both boosting your disgusting month-to-month money otherwise paying off the money you owe.
In case your DTI ratio is simply too high, loan providers you’ll hesitate to offer you a mortgage. They will care and attention that you will not have sufficient earnings to blow month-to-month on your own expenses, improving chances which you can get behind in your home loan repayments.
A top DTI also means that should you manage quality to own one of the several version of mortgages readily available, you are able to be eligible for a lesser loan amount. Once more, the reason being lenders should not overburden your having also much debt.
Should your DTI proportion is actually lowest, though, you’ll increase your chances of being qualified for a variety of financing products. The reduced the DTI ratio, the greater your odds of landing the best possible financial.
Including the fresh payments you make each month to the auto loans, student education loans, family guarantee loans and private financing
- Antique fund: Financing began of the personal lenders. You are in a position to be eligible for a conventional loan you to definitely demands an advance payment off just step 3% of your own residence’s finally cost. If you want the lowest you can rate of interest, you may need a click here to investigate strong credit history, usually 740 or higher.
- FHA finance: These finance try insured by Federal Houses Administration. If for example the FICO credit score is at minimum 580, you may need a down-payment from simply 3.5% of your own home’s latest purchase price when taking out an enthusiastic FHA loan.
- Va fund: This type of financing, insured of the U.S. Institution of Veterans Items, are around for professionals or pros of the You.S. Army or to its widowed partners who possess not remarried. This type of finance need no off payments whatsoever.
- USDA loans: These financing, covered by the You.S. Institution off Agriculture, also require zero advance payment. USDA funds are not accessible to every people, even in the event. You’ll want to buy property inside a part of the latest country that USDA considers rural. Rocket Home loan cannot provide USDA loans.
- Jumbo financing: Good jumbo financing, as the name means, is a big you to definitely, that to have an expense excessive is protected of the Fannie Mae or Freddie Mac computer. In the most common places in 2024, you’ll want to make an application for a jumbo loan if you’re credit more than $766,550. When you look at the large-cost areas of the country — for example La and you can New york — you want a great jumbo mortgage while credit over $step 1,149,825. You want an effective FICO credit history in order to be eligible for one among them fund.
Frequently asked questions about obligations when selecting a good homeWhat would you like to know about loans before you go to get a house? Here are a few preferred concerns.
This may differ by the lenders. But the majority choose that month-to-month expense, as well as your projected brand new monthly mortgage payment, perhaps not equivalent more 43% of disgusting monthly earnings, your income just before your own fees is taken out.
Your debt-to-earnings ratio does not reason for your own month-to-month rent repayments, one medical debt that you might owe, the cable bill, the phone bill, tools, automobile insurance or health insurance.
In order to be eligible for an informed mortgage to the reduced interest rate, repay your financial situation or improve your income to lower which ratio. The reduced the DTI proportion, the higher your odds of being qualified to find the best financial.